Buying Property in Dubai as an Indian Investor: The Ultimate 2026 Guide
Anyone who has spent time researching real estate over the last few years knows how dominant the talk around Dubai has become. Every second post on social media or conversation at family get-togethers centers on purchasing a beachside home or acquiring a studio apartment to generate passive rental income.
On paper, the value proposition is seamless. The flight from Indian metros like Delhi or Mumbai takes just four hours. The UAE charges no tax on rental earnings, and gross returns consistently outperform traditional domestic real estate yields.
However, behind glossy brochures and persuasive marketing campaigns, how does the transaction actually work? Can an Indian buy property in Dubai? Can an Indian resident simply wire funds abroad to acquire a Dubai flat? What regulatory nuances and hidden expenses must you navigate? How to invest in Dubai?
This comprehensive guide breaks down the essential legal facts, banking regulations, and step-by-step procedures required for Indian buyers who want to invest in Dubai real estate.
1. First Things First: Freehold vs. Leasehold Locations
Indian citizens—whether resident individuals or Non-Resident Indians (NRIs)—hold full legal rights to buy real estate in Dubai. Furthermore, holding a UAE residency visa is not a prerequisite for property ownership.
However, foreign buyers must adhere to one central ownership rule: non-UAE nationals can only acquire property within designated Freehold areas.
Dubai’s real estate market operates under two distinct legal arrangements:
- Freehold Property: Grants 100% absolute ownership of both the structure and the underlying land in perpetuity. You retain complete authority to sell, lease, or pass the asset to legal heirs. Most prime neighborhoods in Dubai—including Dubai Marina, Downtown Dubai, Palm Jumeirah, and Jumeirah Village Circle (JVC)—are designated freehold zones.
- Leasehold Property: Grants occupancy and usage rights for a long-term lease period, typically ranging between 30 to 99 years. Once the lease term expires, property ownership reverts to the master land owner.
2. Can Indian Citizen Buy Property in Dubai?
For most Indian buyers, acquiring real estate in Dubai is primarily a strategic capital allocation decision rather than a vacation choice. When compared against Indian metro real estate performance, the financial metrics reveal distinct advantages.
A premium 2-BHK unit in Indian commercial hubs like Gurgaon, Mumbai, or Bengaluru commands valuations between ₹1.5 Crore to ₹3 Crore, yielding modest annual rental returns of 2% to 3% pre-maintenance. Conversely, Dubai offers a far more lucrative return profile:
2.1. Exceptional Rental YieldsGross rental yields across Dubai average between 6% and 9% annually. Well-managed compact units, such as studio or 1-BHK apartments in high-occupancy corridors like JVC or Business Bay, can deliver up to 8% net yields.
2.2. Tax-Free Property RegimeThe UAE government maintains a 0% personal income tax rate, 0% capital gains tax, and 0% recurring municipal property tax on rental returns, allowing investors to keep their operational income intact locally.
2.3. Strong USD-Pegged CurrencyThe UAE Dirham (AED) has been officially pegged to the US Dollar at a fixed rate of 3.67 AED per USD for decades. Investing in Dubai real estate acts as a natural hedge against INR currency depreciation over long holding horizons.
3. Securing UAE Residency Through Real Estate
Beyond capital appreciation and rental yield, qualifying property acquisitions in Dubai enable foreign investors to secure official UAE residency benefits.
3.1. 10-Year UAE Golden Visa (AED 2 Million)Investors purchasing real estate worth AED 2 Million or more (~₹4.5 Crore) qualify for a 10-year renewable UAE Golden Visa. This long-term residency status allows you to sponsor family members and domestic staff without needing a local employment sponsor.
3.2. 2-Year Renewable Residence Visa (AED 750,000)Properties valued at a minimum of AED 750,000 (~₹1.7 Crore) qualify the owner for a standard 2-year renewable residence visa, granting an Emirates ID and access to local services.
3.3. Visa Rules for Mortgaged PropertiesYou can apply for residency visas on mortgaged assets, provided the total paid-up equity in the property satisfies the respective threshold requirements (AED 750,000 or AED 2 Million).
4. Navigating Indian Regulations: LRS, TCS, and Income Tax
While the purchase framework in Dubai is buyer-friendly, Indian residents must adhere strictly to Reserve Bank of India (RBI) guidelines and Income Tax regulations when transferring capital overseas.
4.1. The Liberalised Remittance Scheme (LRS)Under the RBI's LRS framework, an Indian resident individual can legally remit up to USD 250,000 per financial year (April 1 to March 31) abroad for permitted capital transactions, including property purchases (~₹2.05 Crore to ₹2.10 Crore based on prevailing conversion rates).
Pooling Family Limits for Higher Value Properties: If your target property exceeds the single-person LRS limit (e.g., a ₹3.5 Crore flat), family members—including spouses and adult children—can pool their individual USD 250,000 limits, provided all contributors are registered as joint co-owners in the booking documentation and bank wire transfers.
4.2. Tax Collected at Source (TCS) RulesUnder Indian tax law, foreign remittances made under LRS for real estate investments attract a 20% Tax Collected at Source (TCS) on amounts exceeding ₹7 Lakh in a financial year.
TCS is not an additional cost or lost tax; it operates as an advance tax credit. You can offset the collected TCS against your overall tax liability or claim a cash refund when filing your annual Indian Income Tax Return (ITR). However, buyers must account for this upfront liquidity requirement when planning overseas transfers.
4.3. Reporting Dubai Rental Income on Your Indian ITRTax residents of India are taxed on their global income. Consequently, all foreign property holdings must be declared in the Schedule Foreign Assets (FA) of your annual ITR. Furthermore, net rental income earned from your Dubai asset must be disclosed and taxed in India according to your applicable income slab.
Because Dubai imposes 0% local income tax, you cannot claim tax credits under the Double Taxation Avoidance Agreement (DTAA) for local taxes paid, making the rental income fully taxable in India.
5. Step-by-Step Guide: How to Buy Property in Dubai
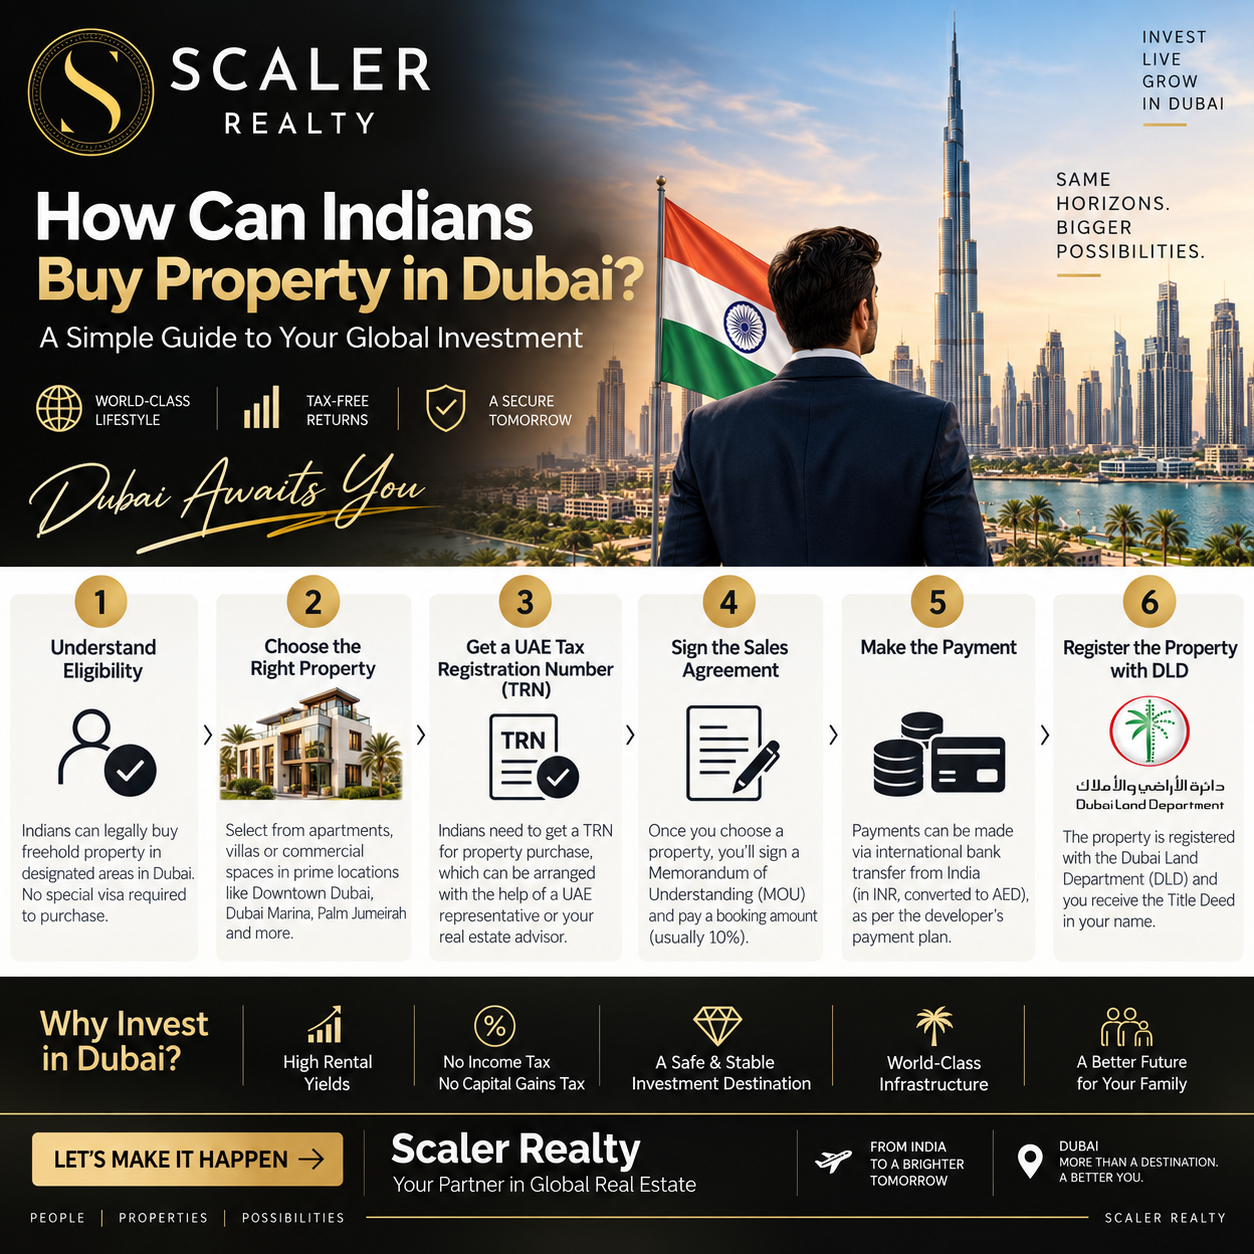
Real estate transactions in Dubai are standardized and regulated by the Dubai Land Department (DLD). The standard purchase process follows four defined phases:
Step 1: Booking and Reservation
Once you select a unit, you reserve the property by paying an initial booking deposit—typically between 10% and 20% of the total purchase price.
Step 2: Signing the Sales Contract (Form F / SPA)
For resale properties, the buyer and seller sign Form F (Unified Sale Contract) and provide a 10% manager's cheque as a security deposit. For off-plan purchases bought directly from a developer, you execute a Sales and Purchase Agreement (SPA) outlining construction timeline milestones.
Step 3: Obtaining the Developer's NOC
Prior to ownership transfer, the developer must issue a No Objection Certificate (NOC). This confirms that the seller has cleared all outstanding service maintenance fees and project liabilities.
Step 4: Property Registration at DLD
The final transfer is executed at a DLD Trustee office or via official online portals upon paying the balance consideration alongside the mandatory 4% DLD registration fee. The DLD then issues the official Title Deed in your name.
6. Critical Financial Checks & Hidden Costs
To evaluate expected net yields accurately, incorporate these core expenses and safeguards prior to committing capital:
- Annual Service Charges: Property owners pay recurring maintenance fees per square foot to cover building upkeep, security, and amenities. Rates typically range between AED 10 to AED 30 per sq. ft., depending on the community tier and amenity level.
- Off-Plan Escrow Protection: When buying off-plan units, verify that payments are remitted directly into a DLD-registered Escrow Account. Developers can only draw funds from these accounts as verified construction milestones are achieved.
- Mortgage Constraints for Non-Residents: While UAE banks offer mortgage products to non-resident Indian buyers, Loan-to-Value (LTV) ratios are generally capped at 50% to 60%. Investors must be prepared to fund the remaining 40% to 50% equity component via self-financing.
7. Conclusion: Making a Smart Investment Decision
Investing in Dubai real estate provides Indian buyers with stable rental yields, long-term currency protection, and foreign asset diversification. However, achieving strong risk-adjusted returns requires looking beyond promotional returns and taking a structured approach to tax compliance, LRS limits, and ongoing maintenance obligations.
Working alongside experienced market professionals like Dhiraj Bidichandani ensures seamless execution—from identifying prime freehold corridors and completing legal due diligence to structuring compliant cross-border remittances.